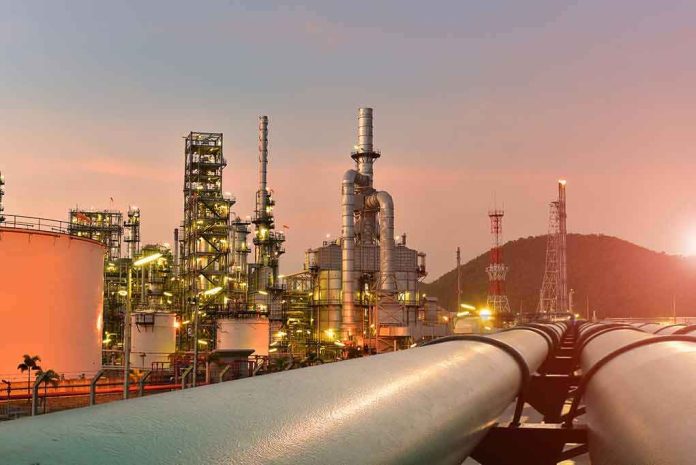
Washington has reached for a Cold War production tool to solve a 21st‑century bottleneck: the Energy Department is deploying Defense Production Act Title III funding to restart idle U.S. refining capacity and expand throughput at operating plants — an industrial, not symbolic, move aimed at adding real gallons of gasoline, diesel, and jet fuel to the domestic market.
The Short Version
- DOE announced up to $150 million in DPA Title III support to boost U.S. refining production, storage, and logistics.
- The department’s stated goal is more domestic supply of gasoline, diesel, jet fuel, and related products on national‑security grounds.
- Title III authorities enable purchase commitments, loans, guarantees, and grants that unlock private co‑investment at refineries.
- DOE expects “millions of gallons per day” of additional output from selected projects, focused on capacity — not short‑term price gimmicks.
What the government is doing and why it matters
The Department of Energy has opened a DPA Title III lane specifically for petroleum production, refining, and logistics to “strengthen America’s fuel supply,” citing national defense as the statutory basis. The announcement authorizes up to $150 million to partner with private operators to restart or expand capacity at U.S. refineries and associated infrastructure — storage tanks, pipelines, and marine terminals that move molecules from crude input to finished product output. This is not a retail rebate or a temporary tax change; it is a capacity intervention. The agency’s own framing is clear: use the DPA to increase the physical ability to produce, move, and store fuels central to the economy and the military.
The mechanism and the targeted outputs are explicit. DOE says funded projects are intended to increase domestic availability of gasoline, diesel, jet fuel, and other refined products, with an aggregate uplift measured in “millions of gallons per day” once projects come online. In a market where refined‑product tightness, not crude availability, has amplified price spikes, incremental barrels per day of reliable U.S. capacity are consequential for both civilian logistics and defense readiness. DOE ties the action to the President’s determination covering petroleum production, refining, and logistics under Title III, which is the portion of the DPA designed to expand essential industrial capacity using federal finance tools.
How Title III financing translates into real capacity
Title III is a specialized industrial policy instrument. It allows the executive branch, through agencies like DOE, to use the Defense Production Act Fund to extend purchase commitments (assured offtake that de‑risks capital projects), direct purchases, loans, loan guarantees, and grants to build or preserve capacity deemed essential to national defense. In the refining context, these tools can close financing gaps for reactivating idled units, debottlenecking crude and vacuum distillation, revamping catalytic crackers or hydrotreaters, or adding tankage and dock capacity that lifts effective throughput. The legal analysis supporting DOE’s action points specifically to 50 U.S.C. § 4533 — the Title III authority for such production‑capacity investments.
Why that matters to an operator is straightforward: refinery upgrades require eight‑figure to nine‑figure capital outlays with execution and market risk. A federal purchase commitment for defined product volumes, or a guarantee that lowers borrowing costs, can move a board and lenders from “wait” to “go.” Title III has a long history in aerospace, microelectronics, and critical minerals; refined fuels now join that list under a national‑security rationale.
What “restart and expand” means in refinery engineering terms
Restarts and expansions are not monolithic. A restart of a mothballed plant may involve integrity checks and replacements on heat exchangers and pressure vessels, catalyst reloading, control‑system modernization, flare and emissions compliance updates, workforce requalification, and feedstock logistics reactivation. An expansion at an operating site could target debottlenecking — incremental capacity added by addressing the limiting unit — or a major project such as revamping a fluid catalytic cracker to swing toward gasoline yield or upgrading distillate hydrotreaters to raise diesel output. Logistics assets — pipelines, storage, and marine terminals — are the connective tissue that lets additional throughput actually reach markets; adding dock capacity or tankage can lift run rates by easing product‑side constraints.
In each case, Title III funds can be the catalytic sliver that unlocks larger private co‑investment, which DOE itself expects. The department’s statement emphasizes partnership with industry to “rapidly bolster” existing infrastructure — indicating co‑funding and commercial risk‑sharing — with the ultimate metric a measurable increase in refined‑product output.
Where this fits in the broader supply–price picture
Refining capacity is a physical constraint. When global refining is tight — due to underinvestment, outages, or geopolitics — cracks (the margin between crude and products) widen and consumer prices respond. Analysts across outlets have noted that recent price surges were driven less by a shortage of crude and more by a shortage of refining capacity and utilization headroom, particularly for diesel and jet fuel. That backdrop explains why DOE is targeting capacity rather than only short‑term price relief mechanisms; the department’s expectation is that additional domestic barrels of gasoline, diesel, and jet fuel improve resilience and, at the margin, moderate prices paid by households and businesses.
Still, capacity is a regional story. A barrel of gasoline produced on the Gulf Coast affects the Midwest differently than the West Coast because of pipeline, marine, and regulatory segmentation. That is why DOE’s inclusion of storage and logistics alongside refining units is material; the agency is signaling that moving product to where it’s needed is part of the deliverable, not an afterthought.
Everyone calls this a gift to oil. The miss: the shortage is not crude, it is refineries. President Donald J. Trump signed the DPA memo today and told the Sioux City rally he is releasing $150M to expand refining capacity and make more diesel and gas. Gas over $4, diesel over $6.
— Frontier Signal (@FrontierSigHQ) October 23, 2026
Timelines, governance, and transparency
Refinery projects are measured in months and years, not weeks. Engineering, procurement, and construction cycles, planned turnarounds, and permitting windows determine pace; one industry assessment pegs restarts or major revamps in the one‑to‑four‑year range depending on scope. The DPA pathway does not waive health, safety, or environmental obligations; it provides financing tools to accelerate viable projects through decision and execution gates. DOE’s announcement notes that selections and specific awards will be made through standard processes, with public details to follow. As of the initial announcement window, no individual refinery award had been posted publicly in the trade press review cited here.
The numbers also deserve precision. DOE set “up to $150 million” for this tranche. Separately, reporters and analysts have referenced a broader energy‑related DPA pool on the order of $1 billion and emphasized heavy private co‑funding; those figures describe context, not a specific DOE obligation to refining in this announcement. The operative financial reality is project‑by‑project contracting under Title III, layered with private capital stacks, to deliver incremental throughput measured in barrels per day.
National defense rationale and expected outcomes
Fuel is a strategic commodity. Military readiness depends on assured access to jet fuel, diesel, and specialized products; civilian logistics, emergency response, and economic activity run on the same molecules. By invoking Title III for petroleum refining and logistics, the administration is asserting that domestic capacity to produce and move these fuels is integral to national defense. The policy objective is straightforward: reduce exposure to global refining bottlenecks and chokepoints by adding reliable U.S. capacity, while leveraging private balance sheets to do it at speed and scale commensurate with risk.
What should readers watch next? Three concrete markers. First, award announcements that identify recipient facilities, dollar amounts, milestones, and expected capacity increases. Second, engineering scope — whether funds target restarts of shuttered refineries, debottlenecking at large Gulf Coast complexes, or logistics that unlock constrained regional markets. Third, integration with market flows — how added output is connected via pipelines, storage, or marine terminals to the regions with the highest sensitivity to diesel and jet supply. Those factors will determine how quickly “millions of gallons per day” become real and where consumers and defense planners feel it first.
Sources:
energy.gov, energynewsbeat.co, washingtontimes.com, argusmedia.com, kmbc.com