The fight over housing affordability is real; the fight over whether a politician who owns multiple homes may argue for reform is a distraction that does not decide the policy question.
At a Glance
- Two separate debates are being conflated: the structural causes of rising housing costs versus the optics of a politician’s personal portfolio.
- Evidence across ideologies converges on constraints to supply—especially restrictive land-use rules—as a central driver of high prices and the vanishing “starter home.”
- Federal support for housing is significant but fragmented; proposals to expand subsidized supply or redirect public funds sit alongside deregulatory agendas.
- Accusations of hypocrisy are politically potent, but they neither prove nor disprove the economics behind affordability reforms.
What Sanders argued—and why critics pounced
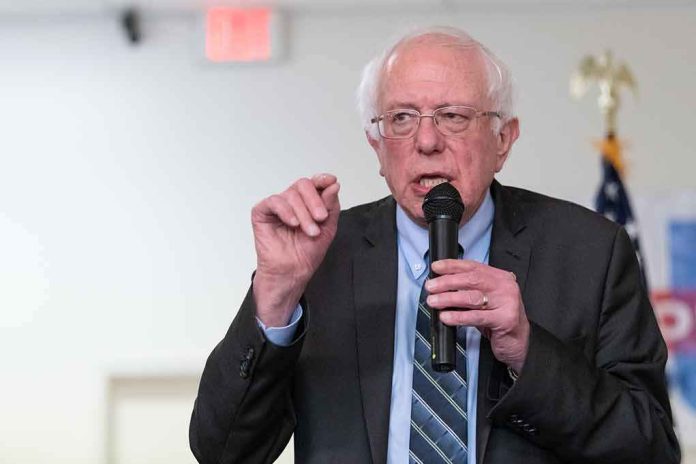
Bernie Sanders has been explicit: homeownership has drifted out of reach for younger and middle-income Americans, and the state should redirect substantial public resources—he has cited military spending and wealth taxes—to build affordable housing at scale. In recent years he has argued for millions of new units and for reshaping federal priorities to finance them. The thrust is redistribution for housing outcomes. Critics answer not with a refutation of the diagnosis, but with an optics indictment: Sanders is a millionaire who owns three homes; therefore, his admonitions about affordability ring hollow. The record supports that biographical point—he has a Burlington residence, a Washington rowhouse, and a lakefront Vermont property—making him a recurring target for “practice what you preach” attacks.
Those attacks travel well in our partisan media economy, but they bypass the substantive hinge: do the mechanisms Sanders and others propose actually lower costs and expand access? The economics of supply, regulation, and finance—rather than who holds the microphone—determine that answer.
How U.S. housing got expensive: supply choke points, not a single villain
Housing affordability deteriorated over decades through a compound of forces. The clearest through-line is supply. Nationally, new construction fell short of household formation in multiple cycles, and the market segment most acutely undersupplied has been small, entry-level homes and lower-cost rentals. The Economic Report of the President documents a decline in starter-home availability concurrent with reduced construction and emphasizes how exclusionary zoning—minimum lot sizes, bans on multifamily units, excessive parking mandates—caps the number and type of homes that can legally be built; fewer permissible units on valuable land mean higher prices and rents.
This diagnosis is not a partisan outlier. Libertarian-leaning analysis finds that tighter land-use regulation correlates with higher real house prices and reduced multifamily stock; municipal literature reviews echo the same mechanism: when rules keep cities from adding homes near jobs and transit, scarcity drives bids upward. A broad cross-ideological coalition has now endorsed loosening overly strict zoning to allow apartments, townhouses, duplexes, and accessory dwelling units—the missing middle of American housing.
What public finance can—and cannot—do
If rules unlock capacity, money determines who can build and who can buy. The federal government already supports housing through tax expenditures (the mortgage interest deduction, property tax deductions), credit backstops (FHA, VA, Ginnie Mae), direct subsidies (Housing Choice Vouchers, public housing capital), and production incentives (Low-Income Housing Tax Credits). Yet this system is fragmented, underserving eligible renters and delivering uneven results across markets. The Urban Institute’s overview underscores the breadth of these tools and their design tradeoffs—who benefits, how benefits phase out, and which geographies capture the value.
Expanding subsidies or redirecting federal outlays can increase production and reduce cost burdens, but scale matters. Legal scholarship pegs annual government spending on affordable housing on the order of tens of billions; meaningfully expanding the affordable stock would require more—either through larger direct appropriations, new dedicated revenue, or major rebalancing within existing budgets. Proposals to stand up millions of deed-restricted units or to deepen voucher coverage must be judged against this arithmetic and the delivery capacity of public and nonprofit developers.
Redistribution versus deregulation is a false choice
Sanders-style agendas emphasize new public investment—sometimes paired with broader fiscal shifts, such as taxing extreme wealth or cutting other categories—to add subsidized units and reduce cost burdens. That can be effective where land-use bottlenecks have been cleared and pipelines exist to translate dollars into doors. In parallel, deregulatory reforms—legalizing multifamily housing near transit, easing lot-size minimums, allowing accessory units, trimming parking mandates—attack the root constraint on market-rate and below-market production. The evidence base suggests the two strategies are complementary: money without zoning reform buys too little on too expensive land; zoning reform without any targeted subsidy leaves the lowest-income households exposed.
Well-intended interventions can also backfire. Inclusionary zoning mandates or rent controls, if designed without attention to elasticity and incentives, can suppress new supply or freeze under-occupied units in place. Some empirical work associates certain inclusionary schemes with reduced overall building and higher prices; strict rent caps can impede mobility and reinvestment. The lesson is implementation craft, not fatalism: calibrate mandates, pair tenant protections with production, and align incentives so that adding homes remains viable.
Does personal wealth negate a housing argument?
The most durable political critique of Sanders focuses on hypocrisy. During earlier campaign cycles, opponents highlighted his millionaire status and three homes to argue he applies different standards to himself than to others. That is fair-game rhetoric, and the underlying facts of ownership have been reported and verified. But as a test of policy validity, it is weak: whether a surtax funds construction, whether a voucher expansion closes rent gaps, or whether zoning liberalization increases unit supply are empirical questions independent of who advances them. Research on political scandal suggests hypocrisy charges move partisan attitudes; they do not resolve technocratic disputes about regulation or public finance.
A useful discipline is to separate messenger from mechanism. Accept the biographical disclosures; then ask: does the proposed policy increase the number of homes where people want to live, and does it reach those who cannot compete in the market unaided? On that standard, the better arguments survive the ad hominem crossfire.
Bernie Sanders is right that 242 U.S. cities now have million-dollar starter homes. Per Zillow, 105 are in California, 41 in New York and 26 in New Jersey. The housing crisis has a home address, and it votes blue. https://t.co/PdMbtfujFt
— Memes & Things (@MemesAndThings_) November 14, 2026
What a serious affordability agenda requires
An effective, durable affordability strategy blends four elements. First, legalize more housing types in more places—by right multifamily near transit and jobs, smaller lots, accessory units, and streamlined approvals—to expand baseline supply. Second, fund targeted production and preservation where the market will not serve: deeply affordable rentals, supportive housing, and aging-in-place rehabs, recognizing that public dollars must be large enough to move the needle and disciplined enough to deliver units on time and on budget. Third, modernize demand-side support—portable vouchers that track inflation and local rent levels, with landlord participation streamlined—so households are not trapped on waitlists. Fourth, align infrastructure and housing: transportation, schools, and utilities planning should anticipate and enable added homes, not trail them by a decade. The record across red and blue jurisdictions shows this mix can bend the cost curve if pursued consistently and at scale.
Bottom line
The disappearance of the American starter home is not a morality play about any one politician’s properties; it is a policy problem produced by decades of rules that constrained building and a financing architecture that poorly targets need. The evidence is clearest on the supply side: where it is legal and feasible to add homes, prices moderate; where growth is throttled, they don’t. The rest of the agenda—subsidies, vouchers, tax design—should be judged by a simple metric: units delivered, households stably housed, and neighborhoods open to newcomers. Personal optics will continue to dominate cable segments. They should not set housing policy.
Sources:
townandcountrymag.com, eagletimes.com, nationalreview.com, foxbusiness.com, benjaminwpowell.com, urban.org, scholarship.law.georgetown.edu, a2gov.legistar.com, cambridge.org